Home › Blog › Best loan apps by need › Low Interest Loan App Philippines: Prices Ranked
Low Interest Loan App Philippines: Prices Ranked
Every app says "low interest". We ranked only the prices lenders actually publish, and turned each one into pesos.
Published November 1, 2026
Scroll through the Play Store's finance section and every loan app says the same thing: "low interest", "affordable", "rates won't burn a hole in your wallet". None of those phrases is a number. Meanwhile your sister paid ₱1,800 to borrow ₱5,000 for three months, your officemate paid less for twice as much from SSS, and nobody can explain why.
This page does one thing: it ranks loan options in the Philippines by the price they actually publish. Not by ads, not by "up to" promises, and not by who pays us. If a lender prints its rate on its website, Google Play listing or official FAQ, it is ranked. If it does not, we say so and leave it unranked. We checked every figure on 31 October 2026 and turned each one into pesos.
Spoiler: the cheapest loans are not apps at all, and the "low interest" apps mostly charge the same legal maximum. That does not make them useless. It means you should know what you are paying for: speed and easy paperwork. This site is a comparison service, not a lender, and some partners pay us a referral fee.
The lowest-interest loan options, ranked by published price
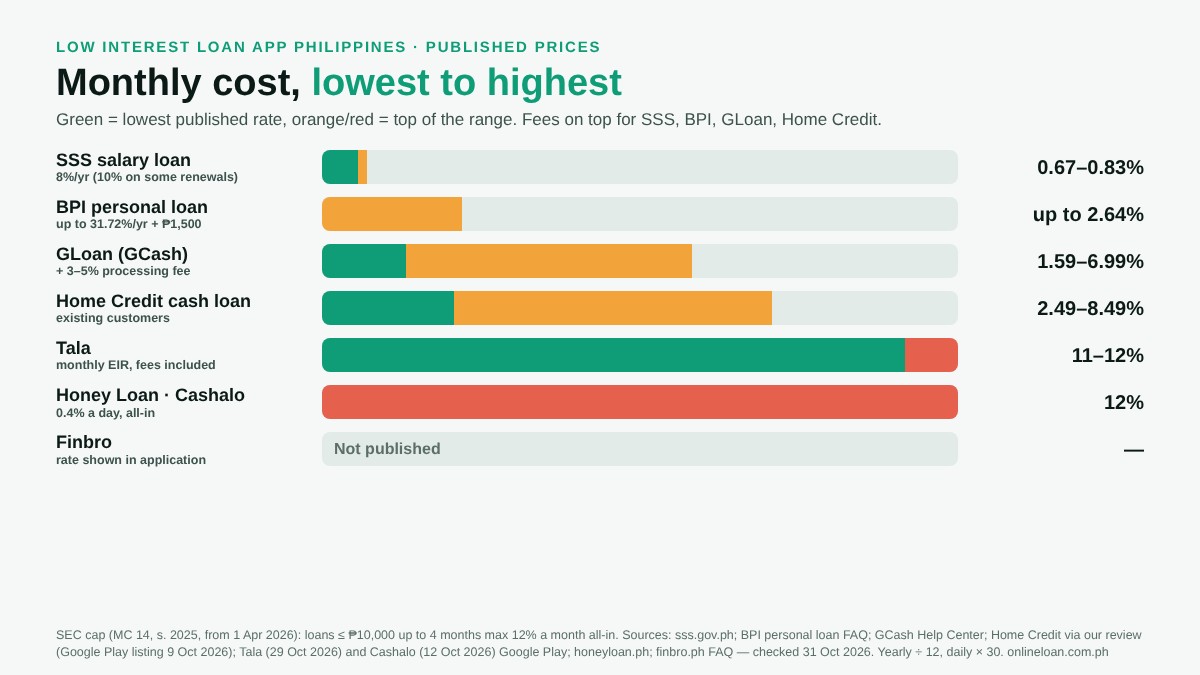
We ranked by the highest monthly rate each provider says it may charge, because that is the price you can be sure of. Where a range is published, both ends are on the card. Banks and SSS sit at the top because they are cheaper; apps follow because they are faster and need less paperwork.
- About 0.67% a month, on the diminishing balance
- 1% service fee, 24 monthly payments
- 10% a year on renewals after a penalty condonation
- Needs 36 posted contributions; takes days, not minutes
- About 2.64% a month at the ceiling
- ₱20,000–₱3,000,000, 12–36 months
- ₱1,500 processing fee deducted
- Income documents and 5–7 working days
- Fuse Financing, on the SEC list
- 3–5% processing fee deducted before release
- No separate app: it is inside GCash
- Only for eligible GCash users
- ₱3,000–₱150,000, 6–48 months
- Processing fee 3%, max ₱1,000 (app listing)
- Cash loans mainly for existing customers
- ₱1,000–₱25,000, up to 120 days
- Processing 3.99–9.99% + 0.23–0.43% a day
- Max APR 141.76%
- Your fees are known only when you get an offer
- Maximum APR 144%, printed on its homepage
- ₱1,000–₱30,000; new clients up to ₱10,000
- 61–364 days to repay
- Warm Cash Lending Corp., SEC No. 2021030009095
- 0.4% a day is the SEC ceiling, not a discount
- 0.2% interest + 0.2% service fee a day
- Up to ₱13,000, 61–180 days
- Max APR 144%, including all fees
- Sofi Financing Inc., SEC No. CS201908275
- Rate and fees shown in the application, before you confirm
- Early repayment with no extra cost
- We cannot rank a price we cannot see
GLoan, Home Credit, Tala and Cashalo are not partners of this site. They are here because a price ranking that left out cheaper non-partners would be useless to you. All the app lenders above are on the SEC's List of Recorded Online Lending Platforms dated 20 October 2026.
How we ranked, and what we refused to rank
- Published only. A rate had to appear on the provider's own website, official help page or Google Play listing on 31 October 2026. Rates in ads, Facebook posts or "from 0%" banners did not count.
- Converted to a month. SSS and BPI publish yearly rates, apps publish daily ones. We divided yearly by 12 and multiplied daily by 30 so you can compare like with like.
- Ranked by the ceiling. The lowest end of a range is what the best customers get; the top end is what you might get. We ranked by the top end and show both.
- No published rate, no rank. Finbro shows its rate only during the application. That is legal and common, but it means we cannot place it in a price ranking.
A warning on apples and oranges. SSS, BPI, GLoan and Home Credit quote a monthly or yearly interest rate, and processing fees come on top. Cashalo, Honey Loan and Tala quote an effective rate that already includes their fees. That is why we also turned everything into total pesos below.
| Option | Published price | About per month |
|---|---|---|
| SSS salary loan | 8% a year + 1% fee | 0.67% |
| BPI personal loan | Up to 31.72% a year + ₱1,500 | Up to 2.64% |
| GLoan | 1.59–6.99% a month + 3–5% | 1.59–6.99% |
| Home Credit | 2.49–8.49% a month + fee | 2.49–8.49% |
| Tala | Monthly EIR 11–12% | 11–12% |
| Honey Loan, Cashalo | 0.4% a day, all-in | 12% |
| Finbro | Not published | — |
Small and fast: what ₱10,000 for 90 days costs
This is the loan most people open an app for: a few thousand pesos, paid back over a couple of paydays. SSS and banks are out here, because BPI starts at ₱20,000 and SSS loans run 24 months. So the real contest is between apps.
| App | Cost on ₱10,000, 90 days | Total repaid |
|---|---|---|
| Tala, lowest listed fees | ₱2,469 | ₱12,469 |
| Honey Loan | ₱3,600 | ₱13,600 |
| Cashalo | ₱3,600 | ₱13,600 |
| SEC ceiling for this loan | About ₱3,600 | About ₱13,600 |
| Finbro | Shown in application | — |
How we worked these out. Honey Loan and Cashalo: ₱10,000 × 0.4% × 90 days, simple daily charge, no late fees. Tala: its lowest listed processing fee (3.99%, ₱399) plus its lowest daily service fee (0.23% × 90 days, ₱2,070); your own fees may be higher, since Tala says its offers are personalised. SEC ceiling: 12% a month for three months under Memorandum Circular No. 14, series of 2025.
That last row is the important one. Since 1 April 2026, loans of ₱10,000 or less with terms up to four months are capped at an effective 12% a month, about 0.4% a day, with all charges never exceeding 100% of the principal. So for small, short loans, 0.4% a day is the legal maximum. Honey Loan and Cashalo publish exactly that. They are not cheap; they are honest about being at the ceiling. More on the rule in our 2026 rate cap explainer.
Key point. On small app loans, the term matters more than the brand. At 0.4% a day, ₱10,000 costs ₱2,440 for 61 days and ₱3,600 for 90 days. Repaying a month sooner saves you more than switching apps usually does.
Want the price upfront? Honey Loan publishes 0.4% a day and a maximum APR of 144%, so you can do the math before you apply.
Check Honey LoanBigger and slower: what ₱20,000 costs over a year
For bigger amounts, the gap between cheap and expensive becomes thousands of pesos. Here is ₱20,000 at each provider's published price.
| Option and term | Cost on top of ₱20,000 | Note |
|---|---|---|
| SSS · 24 months | ₱1,909 | Members only |
| GLoan at 1.59% · 12 months | ₱2,727–₱4,416 | Best rate, if offered |
| Home Credit at 2.49% · 12 months | ₱3,983 | Existing customers |
| BPI at 31.72% · 12 months | ₱5,100 | BPI's ceiling |
| Home Credit at 8.49% · 12 months | ₱13,260 | Top of range |
| Honey Loan · 180 days | ₱14,400 | Repeat clients only |
How we worked these out. SSS: 8% a year on the diminishing balance over 24 equal payments (₱904.55 a month) plus the 1% service fee. BPI: its own example of ₱20,000 over 12 months, total repayment ₱23,600 and ₱1,966.67 a month, which matches its 31.72% ceiling, plus the ₱1,500 fee. Home Credit: monthly rate on the diminishing balance, the method our review found matches its examples, plus a 3% fee (₱600). GLoan: GCash's help page does not say how the monthly rate is applied, so we show both ends: ₱2,127 on a diminishing balance and ₱3,816 if charged on the full amount every month, plus a 3% fee. Honey Loan: ₱20,000 × 0.4% × 180 days.
The surprise is BPI. Its published ceiling is lower than the top of GLoan's and Home Credit's ranges, so if you have documents and can wait a week, a bank loan beats most app quotes. And the SEC's small-loan cap does not cover ₱20,000 at all: it applies only to ₱10,000 or less. A ₱20,000 Honey Loan over 364 days at 0.4% a day would cost ₱29,120 in charges, more than the loan itself. For a fuller comparison by product type, see loan apps vs banks vs pawnshops.
Why SSS and banks win on price, and apps win on speed
SSS charges 8% a year because it lends against your own contributions. You need 36 posted monthly contributions, 6 of them in the last 12 months, and you repay over 24 months. Self-employed and voluntary members qualify too, if they have at least 6 posted months under their current membership type. Our guide to a loan without a payslip explains the route for freelancers.
BPI asks for income documents, such as payslips, an ITR or, for the self-employed, business registration plus bank statements, and it takes 5 to 7 working days. GLoan only appears for GCash users it considers eligible. Home Credit says its cash loans are currently for existing customers.
Apps ask for less: Cashalo and Tala say one valid ID; Honey Loan lists a valid government ID and a mobile number. You pay for that convenience with a higher price. If you need the money today and can repay in weeks, the app's extra cost may be worth it. If you can wait a week, it usually is not.
Fine print that changes the price
Processing fees deducted upfront. GLoan takes 3–5% and BPI ₱1,500 out of the amount you receive. On a small BPI loan the fee hurts: ₱1,500 is 7.5% of ₱20,000. Cashalo says it releases the full amount with "no kaltas".
Examples that do not match the headline. Tala's sample says a 3.99% processing fee and 0.43% a day, but its numbers, ₱99.90 and ₱140.30 on ₱1,000 over 61 days, match 9.99% and 0.23%. The total, ₱1,240.20, is still the figure to trust. Crezu, a matching service, lists lender rates of 12% to 36% APR, yet its own example turns ₱10,000 into ₱15,000 in three months. Always trust the peso total in your disclosure statement over any headline.
"From 0%" offers. Honey Loan's offer table says new-client interest starts "from 0%", without explaining when. Treat 0.4% a day as the price unless your disclosure statement shows less. We look at these promos in our guide to 0% first loans.
Early repayment. Finbro says you can repay in full before the due date at no extra cost, and Tala says you only pay for the days you need. Home Credit charges ₱300, according to our review. GCash's help page offers interest cashback if you repay GLoan in full at least a month before the due date; our GCash guide notes that early repayment may carry a processing fee.
Late fees. SSS charges 1% a month on late amortizations. GLoan adds 1% of the loan per missed due date plus 0.15% a day. Tala charges 5% of the outstanding balance after the term. Late fees can turn the cheapest loan into an expensive one; read what happens if you miss a payment.
Real scenarios: which cheap option is cheapest for you
Marites, 38, call center supervisor, needs ₱20,000 for her son's enrollment in three weeks. She has 10 years of SSS contributions. The SSS loan costs her about ₱1,909 over two years. An app would cost many times more. Three weeks is enough time, so she applies in My.SSS.
Dennis, 30, ₱6,000 short for a car repair, payday in 12 days. He has no time for SSS. At 0.4% a day, ₱6,000 for 61 days costs ₱1,464, our calculation; if early repayment cuts the charge, it costs less. He also checks whether GLoan appears in his GCash app, since its lowest rate is far below 12% a month.
Bea, 27, already has a Home Credit installment. As an existing customer, she may see a Home Credit cash loan offer. At 2.49% a month, ₱15,000 over 12 months costs ₱2,537 in interest, per our review's example. At 8.49% it would be ₱9,495. She compares the rate in her offer with BPI's ceiling before accepting.
Rico, 45, comparing three apps that all say "low interest". He ignores the slogans and asks one question of each: what is the total repayment on ₱5,000 for 61 days? Honey Loan's published rate gives ₱1,220. Tala gives a personalised figure. Finbro shows its rate in the application. He takes the lowest total he actually sees, not the lowest claim.
Other apps you will see
These apps are on the SEC list of 20 October 2026. We did not re-check their prices for this ranking, so they are not ranked here; see our reviews and their disclosure statements.
Checklist: how to find the cheapest loan you can actually get
- Start with SSS if you are a member with 36 posted contributions and can wait a few days.
- If you have income documents and need ₱20,000 or more, check a bank such as BPI.
- Open GCash and see whether GLoan is offered to you, and at what rate.
- For a small, fast loan, compare the total repayment in pesos, not the slogan.
- Remember that on loans of ₱10,000 or less up to four months, no lender may charge more than 12% a month.
- Subtract any processing fee from what you will actually receive.
- Pick the shortest term you can repay; every extra day costs money.
- Check the lender's name on the SEC list before you sign; see our legit loan apps hub.
Quick answers
What is the lowest-interest loan app in the Philippines? Among apps with published prices, GLoan has the lowest starting rate, 1.59% a month plus a 3–5% processing fee, but only for eligible GCash users. Outside apps, the SSS salary loan is cheaper still at 8% a year.
Which loan app is cheapest for a small, short loan? For loans of ₱10,000 or less up to four months, the legal maximum is 12% a month. Honey Loan and Cashalo publish exactly 0.4% a day. Tala's fees are personalised and can be lower.
Is 0.4% a day low interest? Not really. It equals about 12% a month and a maximum APR of 144%. It is the SEC ceiling for small, short loans, so it is a fair price for an app, but banks and SSS are far cheaper.
What is Finbro's interest rate? Finbro does not publish it. Its FAQ says you see the rate and fees during the application, before you confirm the agreement.
Is Honey Loan legit? Yes. Honey Loan is listed under Warm Cash Lending Corp., SEC No. 2021030009095, on the SEC's List of Recorded Online Lending Platforms dated 20 October 2026.
Why do banks charge less than apps? They lend larger amounts for longer, check income documents and take days to approve. Apps price in the speed and the risk of lending on one ID.
Want a published price? Start with Honey Loan, or compare offers and pick the lowest total you actually see. For the meaning of EIR, APR and add-on rates, read our interest rates explainer.
Sources: SSS Salary Loan page, sss.gov.ph (checked 31 Oct 2026); BPI Personal Loan new applicants FAQ, bpi.com.ph (checked 31 Oct 2026); GCash Help Center, GLoan fees and interest rate (checked 31 Oct 2026); Home Credit figures from our Home Credit review (based on its Google Play listing updated 9 Oct 2026 and homecredit.ph disclosures); Tala Google Play listing (updated 29 Oct 2026); Cashalo Google Play listing (updated 12 Oct 2026); honeyloan.ph homepage (checked 31 Oct 2026); finbro.ph FAQ (checked 31 Oct 2026); crezu.ph homepage (checked 31 Oct 2026); SEC List of Recorded Online Lending Platforms as of 20 October 2026; SEC Memorandum Circular No. 14, series of 2025, as reported by GMA News (11 Dec 2025). Peso examples other than the providers' own are our calculations. This article is general information, not legal or financial advice.
Ready to check your offer with Honeyloan?
Honeyloan
Compare available lending offers
Review the final repayment amount and terms on the provider's website