Home › Blog › Best loan apps by need › Best Online Loan Apps Philippines 2026: Top 5 Offers
Best Online Loan Apps Philippines 2026: Top 5 Offers
Five loan offers you can apply for with one valid ID, two of them from SEC-recorded lenders. Here is what each one costs in pesos and who it suits best.
Published November 1, 2026
You check your wallet on a Tuesday and do the math. Payday is the 15th, it is the 6th, and the electric bill, a ₱2,800 tuition balance and your phone plan are all due before then. You need ₱5,000, and you need it in a day or two, not after a bank asks you for three months of payslips. So you open the Play Store, type "online loan app", and get a wall of near-identical apps all promising "fast approval" and "low interest".
This page is the shortcut. We picked five online loan offers you can apply for through this site, checked each one against the SEC's list and the provider's own website on 31 October 2026, and put the real peso costs next to each other. Two are direct lenders recorded with the SEC. Three are matching services that send one application to several lenders at once. We also show the well-known apps outside our partner list, so you can see where each pick stands.
One thing up front: this site is a comparison service, not a lender. Some partners pay us a referral fee when you apply, and the order below is based on the criteria explained further down.
The 5 best online loan offers in the Philippines right now
Each card shows who actually lends you the money, the range you can ask for, and the one thing to watch. "Lender" means the company that signs the loan with you. "Matching service" means a free website that passes your application to lenders it works with. The lender you end up with sets the final rate.
- Sofi Financing Inc., SEC No. CS201908275
- "No payslip document required" on its site
- Decision in 10 minutes to 1 working day
- Minimum payment can move your due date 7, 14 or 30 days
- Rates are shown only during the application
- Warm Cash Lending Corp., SEC No. 2021030009095
- 0.4% a day, maximum APR 144%, published upfront
- New clients up to ₱10,000, repeat up to ₱30,000
- 61 to 364 days to repay
- Age 21 to 70 only
- Free to use, no service fee from Crezu
- Terms of 91 to 120 days, per its site
- Needs a phone number, valid PH ID, bank account
- Not a lender: check the lender it sends you to
- Free, does not lend from its own account
- Partner lenders offer 91 to 180 days
- Usually one valid ID and a selfie
- Its APR range is wide: 0% to 427%
- Free, no credit history required
- Lender terms of 91 to 120 days
- Some partners may offer a first loan at 0%
- APR range listed as 4% to 916%
- Free list of offers from partner lenders
- Advertises a 0% first loan from some partners
- Operator not named on its site
How we picked these 5
We did not rank by who pays us the most. We scored each offer on what matters when you are short on cash and in a hurry.
- Who is behind it. Direct lenders had to appear on the SEC's List of Recorded Online Lending Platforms dated 20 October 2026. Matching services had to say clearly on their site that they are not lenders.
- Paperwork. How many documents you need. All five work with one valid government ID, and none asks for a payslip upfront.
- Price transparency. Does the provider publish a rate, a maximum APR or a worked example before you apply? Honey Loan does. Finbro shows its rate during the application.
- Range and flexibility. How much you can borrow, for how long, and whether there is a way out if payday is late.
- Where the money lands. GCash, Maya and bank transfers all count.
That is why the two SEC-recorded lenders sit at the top, and why the matching services come with a "check the lender" warning. If you want the full list of registered apps, our legit loan apps hub has it, and this guide shows how to check any app yourself in two minutes.
Top 5 compared side by side
| Offer | What it is | Amount |
|---|---|---|
| Finbro | SEC-recorded lender | Not published |
| Honey Loan | SEC-recorded lender | ₱1,000–₱30,000 |
| Crezu | Matching service | ₱500–₱25,000 |
| Loanonline | Matching service | Up to ₱25,000 |
| Binixo | Matching service | From ₱1,000 |
| Offer | Repayment term | Who can apply |
|---|---|---|
| Finbro | Set in your offer | 20–70 · regular income |
| Honey Loan | 61–364 days | 21–70 · Filipino citizen |
| Crezu | 91–120 days | PH ID · bank account |
| Loanonline | 91–180 days | ID + selfie |
| Binixo | 91–120 days | 18+ · Filipino citizen |
What a ₱5,000 online loan really costs
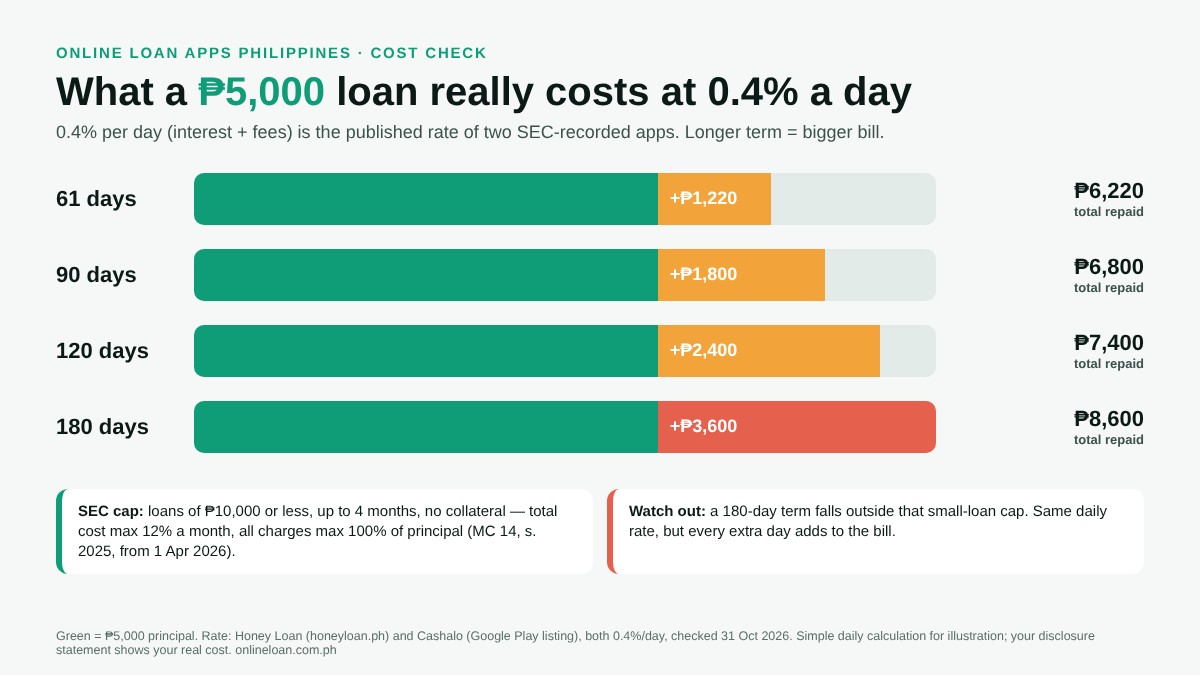
Here is the part most app pages skip. Honey Loan and Cashalo, two SEC-recorded apps, both publish the same price: 0.4% a day, made up of interest plus a service fee. That works out to about 12% a month, which is exactly the SEC ceiling for small, short loans. So 0.4% a day is a realistic yardstick for what a regular app loan costs in 2026.
| Term | Fees on ₱5,000 | Total you repay |
|---|---|---|
| 61 days | ₱1,220 | ₱6,220 |
| 90 days | ₱1,800 | ₱6,800 |
| 120 days | ₱2,400 | ₱7,400 |
| 180 days | ₱3,600 | ₱8,600 |
Our calculation: ₱5,000 × 0.4% × number of days, simple daily charge, no late fees. Honey Loan's own worked example matches this method: ₱3,000 for 180 days costs ₱2,160 in interest and fees, so you repay ₱5,160 in monthly installments of ₱860.
Two things jump out. First, the daily rate stays the same, but the bill grows with every day you keep the money. Pay back in 61 days instead of 180 and you keep ₱2,380 in your pocket. Second, the SEC's small-loan cap only covers loans of ₱10,000 or less with terms of up to four months. A six-month loan is outside it. For the full rules, see our explainer on the 2026 interest rate cap and how to read EIR and APR.
Key point. Pick the shortest term you can actually afford. At 0.4% a day, the same ₱5,000 costs ₱1,220 over 61 days and ₱3,600 over 180 days. The cheapest loan is usually the one you repay first.
Know your number, then compare. Most offers here go up to ₱25,000, and two lenders publish their prices. Check what you qualify for before you commit.
Compare offersThe 5 offers in detail
1. Finbro: the no-payslip pick from an SEC-recorded lender
Finbro is run by Sofi Financing Inc., listed on the SEC's online lending platform list under SEC No. CS201908275, with Certificate of Authority No. 1324 on its own site. It is a direct lender, so the loan contract is with Finbro itself.
Its main selling point is paperwork. The site says you need one valid ID and a selfie, with "no payslip document required". Accepted IDs listed in its FAQ include SSS, UMID, driver's license, passport, national ID and postal ID. You must be a Filipino citizen aged 20 to 70, employed or with a regular source of income.
Processing takes from 10 minutes to one working day, and disbursements to GCash, Maya or a bank account are real-time once approved. The feature we like most is the minimum payment. If you cannot pay in full on the due date, a minimum payment pushes your next payment date by 7, 14 or 30 days. You also pay nothing extra for settling early.
The catch: Finbro does not publish its interest rate or processing fee. You see them during the application, before you sign. Read that disclosure statement line by line. More detail is in our Finbro loan review.
2. Honey Loan: published prices and room to grow
Honey Loan appears on the SEC list under Warm Cash Lending Corp. (SEC No. 2021030009095, recorded 27 April 2021). Its website shows registration No. 2021030009095-02 and Certificate of Authority No. 3472.
It publishes its pricing right on the homepage, which is rarer than it should be: 0.4% daily interest, a maximum APR of 144%, and "no hidden fees or commissions". Loans run from ₱1,000 to ₱30,000. New clients can borrow up to ₱10,000, and repeat clients up to ₱30,000. The repayment period is listed as 61 to 364 days, in installments or all at once.
Requirements are short: a Filipino citizen aged 21 to 70, a valid government ID, an active mobile number and an account on its website. The site says checking an application usually takes 2 to 3 minutes.
What to watch: its offers table says new-client interest starts "from 0%" but does not explain when that applies. Treat 0.4% a day as the real price unless your disclosure statement shows something lower. And remember that long terms are where the cost piles up.
3. Crezu: send one form, see several lenders
Crezu is a loan search and comparison website, not a lender. It is a brand of Fininity OÜ, a company registered in Estonia. You fill in one form, and Crezu passes it to partner lenders who can make you an offer.
On its Philippine site, Crezu lists loans from ₱500 to ₱25,000 with terms of 91 to 120 days, and says it charges you no service fee. You need internet access, a valid Philippine ID and a bank account. Its own example, ₱10,000 over three months with ₱15,000 repaid in total, is a good reminder of why the lender's disclosure matters more than any headline rate.
Use Crezu when you have been declined once and want more chances in one go. Before you accept any offer, look up the lender's name on the SEC list.
4. Loanonline: ID and selfie, several partner lenders
Loanonline.ph says plainly that it "is not a loan provider" and does not lend from its own account. It is operated by SIA JEFF, a company registered in Latvia, and is free to use.
Its site advertises loans of up to ₱25,000, with partner lenders offering terms of 91 to 180 days. Depending on the lender, one valid ID and a selfie are enough. The APR range it lists is very wide, from 0% to 427%, which tells you how much the final price depends on which lender picks up your application.
5. Binixo: a route in for first-time borrowers
Binixo says it "is not a bank or lender". It is operated by INFINSA LTD, registered in Cyprus, and shows you a list of offers from lenders. The service is free, and it says no credit history is required, which helps if you have never borrowed before.
Lender terms run from 91 to 120 days. Its calculator goes from ₱1,000 up to ₱50,000, while its page title says up to ₱25,000, so expect most offers in the lower range. Its example: ₱1,000 for three months at 48% a year comes to ₱1,120. The full APR range it lists is 4% to 916%, so compare carefully. If this is your first loan ever, read our first-time borrower guide first.
Bonus: Finami
Finami is a matching service built on the same model as Binixo: a free list of partner offers from ₱1,000 to ₱25,000, with a 0% first loan "may be offered" by some lenders, subject to approval. Its site does not name the operating company, so we keep it as a bonus, not a main pick. Our Finami review explains how 0% promos really work.
Seen enough? All six offers above are one tap away, with requirements, a calculator and full terms on each page.
Compare offersBest online loan app by what you need
Loan app with no payslip
Finbro says it needs no payslip at all, only one ID and a selfie. Honey Loan also says an ID is enough. Freelancers, sellers and self-employed borrowers can start there. Our documents guide lists what else lenders may ask for.
First loan, no credit history
New borrowers usually get a small first limit. Honey Loan caps new clients at ₱10,000. Binixo says it needs no credit history and passes you to lenders who accept first-timers. Small amounts and on-time payments are how limits grow. Here is how to raise your approval chances.
The biggest amount
Among our five picks, Honey Loan has the highest published ceiling, ₱30,000 for repeat clients. If you need ₱50,000 or more, a bank or an installment lender is often cheaper. See apps vs banks vs pawnshops.
Cash straight to GCash
Finbro pays out to GCash, Maya or a bank account in real time after approval. If you would rather borrow inside GCash itself, compare our guide to GLoan, GGives and GCredit.
How our picks compare with popular apps
You will also see these names in the Play Store. They are not partners of this site, but all of them are on the SEC list of 20 October 2026, and they make a useful benchmark.
Cashalo is a good reference point. Its Google Play listing (updated 12 October 2026) gives a worked example: ₱2,000 over 90 days costs ₱360 in interest plus ₱360 in service fees, so you repay ₱2,720. That is the same 0.4% a day as Honey Loan. Cashalo's ceiling is ₱13,000, below Honey Loan's ₱30,000 for repeat clients. Tala and Home Credit figures above come from our own reviews of their app listings.
Real scenarios: which offer fits you
Mika, 27, online seller, needs ₱5,000 for stock before a payday sale. She has no payslip, only GCash income. Finbro is her first stop because it asks for no payslip. Finbro shows its rate during the application; if her offer comes in at 0.4% a day and she repays in 61 days, she pays about ₱1,220 on top. If the sale goes well and she clears it early, she pays less.
Jun, 34, BPO agent, a ₱9,000 dental bill, payday in 10 days. He has never borrowed from an app. Honey Loan lets new clients take up to ₱10,000, and the price is published. Even if he picks a 61-day term and pays it off on payday, he should check that early repayment reduces the charges in his disclosure statement before signing.
Ana, 41, declined by two apps last month. Instead of downloading five more apps, she sends one form through Crezu or Loanonline and sees which lenders answer. She checks each lender's name on the SEC list before saying yes, and ignores any offer that asks for an upfront fee.
Carlo, 23, first job, ₱3,000 to cover a week. No credit history. He tries Binixo for lenders that accept first-timers and keeps the term short. On a ₱3,000 loan at 0.4% a day, 61 days costs ₱732, while 180 days costs ₱2,160.
Red flags that should stop you
Every pick here asks you to sign with a lender that is on the SEC list. Walk away if any app asks for a fee before releasing the loan, wants access to your contacts or photo gallery, has no SEC registration number or Certificate of Authority on its site, or threatens you with jail. Unpaid debt alone is not a crime in the Philippines, as we explain in this guide. For more warning signs, read loan scam red flags.
If you are already late on a payment, do not borrow from a second app to pay the first. Read what happens when you miss a payment and talk to the lender first.
Checklist before you tap "Apply"
- Decide the exact amount you need, not the maximum the app offers you.
- Look up the lender's company name on the SEC's List of Recorded Online Lending Platforms.
- Find the total repayment amount in pesos in the disclosure statement, not just the daily or monthly rate.
- Choose the shortest term that fits your next one or two paydays.
- Check that the loan is released in full, with no fees deducted upfront that you did not agree to.
- Ask what happens if you pay late, and whether there is a minimum payment or extension option.
- Check whether repaying early lowers what you owe.
- Never pay any "processing" or "release" fee before you get the money.
Quick answers
What is the best online loan app in the Philippines? It depends on your situation. Among our picks, Finbro is the strongest choice if you have no payslip, and Honey Loan if you want the price published upfront or a bigger repeat loan. Both are on the SEC list dated 20 October 2026.
Is Finbro legit? Yes. Sofi Financing Inc., operating as Finbro.ph, is on the SEC's List of Recorded Online Lending Platforms under SEC No. CS201908275.
Is Honey Loan legit? Yes. Honey Loan is listed under Warm Cash Lending Corp., SEC No. 2021030009095, on the same SEC list dated 20 October 2026.
Which loan app needs only 1 valid ID? Finbro says one valid ID and a selfie are enough, with no payslip. Honey Loan also says you only need your ID. Loanonline's partner lenders usually ask for one ID and a selfie.
How much interest will I pay on a ₱5,000 loan? At 0.4% a day, the rate Honey Loan and Cashalo publish, you pay about ₱1,220 over 61 days or ₱3,600 over 180 days. Your actual cost is in your disclosure statement.
Are Crezu, Binixo and Loanonline lenders? No. They are free matching services that pass your application to partner lenders. The lender that approves you sets the rate, so check its name on the SEC list.
Not sure yet? Compare offers side by side, check the total repayment amount on the provider's own page, and choose the one you can repay on time.
Sources: SEC List of Recorded Online Lending Platforms as of 20 October 2026; finbro.ph homepage and FAQ (checked 31 Oct 2026); honeyloan.ph homepage (checked 31 Oct 2026); crezu.ph, binixo.ph, loanonline.ph and finami.ph homepages (checked 31 Oct 2026); Cashalo Google Play listing (updated 12 Oct 2026) and cashalo.com rate cap notice; SEC Memorandum Circular No. 14, series of 2025 (effective 1 April 2026), as summarized by Cashalo; Tala and Home Credit figures from our earlier reviews of their app listings. Peso examples other than the providers' own are our calculations. This article is general information, not legal or financial advice.
Ready to check your offer with Finbro?
Finbro
Compare available lending offers
Review the final repayment amount and terms on the provider's website