Home › Blog › Best loan apps by need › 0% Interest First Loan Philippines: Where It's Real
0% Interest First Loan Philippines: Where It's Real
Free first loans are real, but small, short and strict. Here is where a 0% offer is written down, and what you pay if you miss the first due date.
Published November 1, 2026
Your cousin swears she borrowed ₱3,000 from an app and paid back exactly ₱3,000. Now your rent is short by ₱4,500, payday is three weeks away, and every loan ad on your feed shouts "0%" in huge letters. So you wonder: is a free first loan real, or is it the hook before the real bill?
The honest answer is both. A 0% first loan does exist in the Philippines, and a few companies put it in writing. But it almost always comes with a small cap, a short window and one condition that matters more than all the others: you must repay in full, on time, on the first due date. Miss it, and the "free" loan turns into a normal app loan, sometimes from day one.
We checked the websites and app pages of every offer below on 31 October 2026 and matched each lender against the SEC's List of Recorded Online Lending Platforms dated 20 October 2026. This site is a comparison service, not a lender, and some partners pay us a referral fee when you apply. The order below follows the criteria explained further down, not who pays.
Where a 0% first loan is offered right now
Each card shows who actually lends the money, the exact 0% wording the company uses, and the catch. "Lender" means the company that signs the loan with you. "Matching service" means a free website that sends your application to partner lenders, and the partner decides whether a 0% offer applies to you.
- Online Loans Pilipinas Financing Inc., SEC No. CS201726430, CA No. 1181
- FAQ: "zero interest and no processing fee" for first-time customers
- Homepage: 0% "if you pay back on the first payment date"
- Repeat borrowers up to ₱20,000, 61 to 183 days
- Not our partner. Max APR 143% a year once the promo is gone
- "0% interest if you pay back on the first payment date"
- Free to compare and send a request
- Age 18+, ID and bank account, credit history not considered
- 0% "may be offered" by partners, subject to approval
- Operator not named on its site. Check who approves you
- Calculator shows "0%*" interest for a first loan
- Operated by INFINSA LTD (Cyprus), free for users
- Lender terms of 91 to 120 days
- 0% "may be offered" by partners, subject to approval
- Full APR range listed as 4% to 916%
- Headline: "1st Credit with 0%"
- Footnote: first loan "can be free of charge for new clients"
- Free, no service fee, 91 to 120 days
- Its own ₱10,000 example costs ₱5,000 in 3 months
- Warm Cash Lending Corp., SEC No. 2021030009095
- Offers table: new clients "starting from 0%"
- Standard price published: 0.4% a day, max APR 144%
- Site does not say when the 0% applies
How we picked and ranked these offers
- Is the 0% in writing? We only listed companies whose own website or app page, opened on 31 October 2026, states a 0% or free first loan. Third-party blog lists did not count.
- How clear are the conditions? A promo that names the amount, the fee and the deadline beats one that says "may be offered".
- Who lends the money? Direct lenders had to appear on the SEC list dated 20 October 2026. Matching services had to say clearly that they are not lenders.
- What happens after the promo? We gave credit to companies that publish their normal price, so you can work out the cost of slipping.
That is why Online Loans Pilipinas leads on clarity even though it is not a partner of this site, and why Finami is our pick to compare: one free form puts you in front of several partner lenders, some of which may approve a first loan at 0%. For the full list of registered apps, see our legit loan apps hub.
The offers compared side by side
| Offer | 0% wording | Who decides |
|---|---|---|
| Online Loans Pilipinas | Zero interest, no fee | The lender itself |
| Finami | 0% may be offered | Partner lender |
| Binixo | 0% may be offered | Partner lender |
| Crezu | Can be free of charge | Partner lender |
| Honey Loan | Starting from 0% | The lender itself |
| Offer | Amount | Term |
|---|---|---|
| Online Loans Pilipinas | ₱1,000–₱7,000 first | 61–183 days |
| Finami | ₱1,000–₱25,000 | 3–12 months |
| Binixo | From ₱1,000 | 91–120 days |
| Crezu | ₱500–₱25,000 | 91–120 days |
| Honey Loan | ₱1,000–₱10,000 new | Up to 12 months |
What the conditions usually are
No two promos are written the same way, but the ones we read share a pattern. Treat these as the questions to ask before you tap "Apply".
1. It is for your first loan only
Every 0% offer above is for new customers. After that, loans are priced normally, and an old account with the lender usually means no promo.
2. The amount is capped low
Online Loans Pilipinas' website FAQ says first-time applicants can borrow ₱1,000 to ₱7,000. Its App Store listing, also checked on 31 October 2026, says ₱1,000 to ₱10,000 in its FAQ. Honey Loan caps new clients at ₱10,000. The bigger limits, up to ₱20,000 or ₱30,000, are for repeat borrowers paying the normal rate.
3. The deadline is the first payment date
Online Loans Pilipinas and Finami use the same words: 0% "if you pay back on the first payment date". On an installment loan, that means repaying the whole amount at the first due date, not just the first installment. If you follow the normal schedule instead, you pay normal interest.
4. "Interest" and "fees" are not the same thing
Some promos remove interest but keep a processing fee. Online Loans Pilipinas promises "no processing fee" too. Elsewhere, the number that matters is the total you repay in pesos, not the word "0%". Our interest rates explainer shows how to read it.
5. A matching service cannot promise it
Finami, Binixo and Crezu are not lenders. Their 0% lines say the first loan "may be offered" or "can be free" by partners, "subject to approval and the lender's terms". You only know whether you got 0% when the actual lender shows you its offer.
6. Lateness kills it
Finami and Binixo list a late-payment charge of 0.1% of the amount owed. Online Loans Pilipinas' FAQ warns that early repayment "may" carry a fee set in your loan agreement. None of the pages we read promise that a late borrower keeps the 0%. Assume it is gone the moment you miss the date.
Key point. A 0% first loan is free only if three things are true: the lender itself confirms 0% in your disclosure statement, the total to repay equals what you borrowed, and you pay it all back on the first due date. If any one is missing, price it as a normal loan.
Want to try for a 0% first loan? Finami sends one free request to partner lenders. Some may approve a first loan at 0%. You see the real terms before you sign.
Check Finami offersThe honest math: what happens if you miss the promo
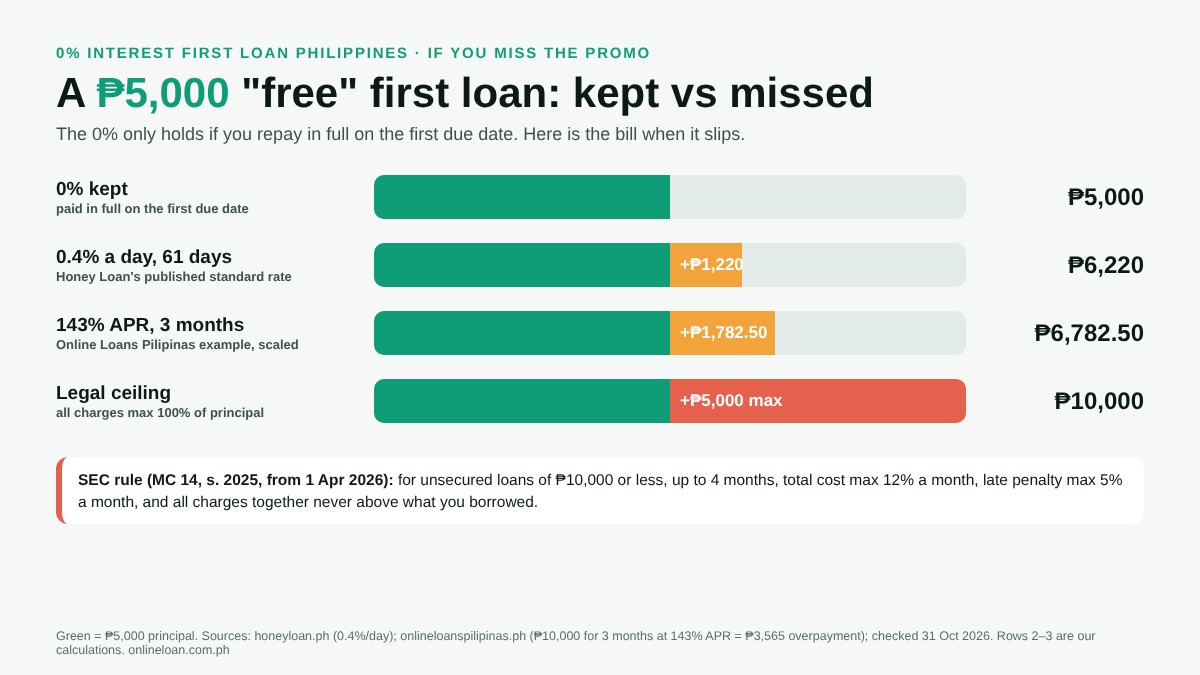
Here is what the ads skip. We took a ₱5,000 first loan and priced it four ways using published numbers.
| Scenario on ₱5,000 | Extra cost | Total you repay |
|---|---|---|
| 0% kept, paid on time | ₱0 | ₱5,000 |
| Normal rate, 0.4% a day, 61 days | ₱1,220 | ₱6,220 |
| Normal rate, OLP example, 3 months | ₱1,782.50 | ₱6,782.50 |
| SEC ceiling on all charges | ₱5,000 | ₱10,000 |
How we calculated it. The 0.4% a day row uses Honey Loan's published daily rate: ₱5,000 × 0.4% × 61 days = ₱1,220. The Online Loans Pilipinas row scales its own representative example (₱10,000 for 3 months at 143% APR costs ₱3,565 in total overpayment) to ₱5,000, assuming the cost grows in proportion to the amount. The last row is the legal ceiling for small loans under SEC Memorandum Circular No. 14, series of 2025 (effective 1 April 2026): for unsecured loans of ₱10,000 or less with terms of up to four months, all charges together can never exceed 100% of the principal. Late penalties are capped at 5% a month on top of that rule, so a ₱5,000 balance adds at most ₱250 a month in penalties.
The gap between "free" and "normal" on ₱5,000 is ₱1,200 to ₱1,800, real money in a tight month. Missing by a few days can mean the normal charge for the whole term, depending on your agreement. Payday moving from the 15th to the 17th, or a late-night transfer that lands the next morning, is enough. The SEC ceiling stops runaway charges, but it is a ceiling, not a target. More on the rules in our 2026 interest rate cap explainer.
The offers in detail
Online Loans Pilipinas: the clearest written 0% offer
Online Loans Pilipinas Financing Inc. appears on the SEC list of 20 October 2026 under SEC No. CS201726430, and its website shows Certificate of Authority No. 1181. It is a direct lender, so the 0% decision is its own, not a partner's.
Its FAQ says: "For our first time customers we offer zero interest and no processing fee loan. Try our service for free!" The homepage adds that the 0% applies "if you pay back on the first payment date". First-time applicants can borrow ₱1,000 to ₱7,000 according to the website FAQ. The App Store listing says ₱1,000 to ₱10,000 for first-timers, so expect the lower figure and let the app tell you your limit.
The standard product runs from ₱1,000 to ₱20,000 over 61 to 183 days. The website gives a maximum APR of 143% a year including all commissions, with an example: ₱10,000 over 3 months at 143% APR means three payments of ₱4,522 and ₱13,565 in total. The App Store listing instead gives a maximum APR of 36% for 12-month loans and mentions a ₱250 processing fee included in the total cost. We report both. Your disclosure statement is the final word.
The catch: it is not a partner of this site. If you search for it in an app store, check that the developer name matches the company above.
Finami: our pick to compare 0% first-loan offers
Finami is a free matching service. You enter an amount from ₱1,000 to ₱25,000, and it shows offers from partner lenders whose services run from 3 to 12 months. Its headline reads "0% interest if you pay back on the first payment date", and the footnote says the first loan "may be offered at 0% by our lending partners, subject to approval and the lender's terms".
You need to be 18 or older, a Philippine citizen with an ID, internet access and a bank account. The site says credit history is not considered. Its legal text lists an APR range of 4% to 916% a year and a late charge of 0.1% of the amount owed. The site does not name its operator, so check the lender it sends you to. Our Finami review walks through it.
Binixo: 0% for first-timers, through partners
Binixo is run by INFINSA LTD, registered in Cyprus, and says it is not a bank or lender. Its calculator shows a "0%*" interest rate, with the same footnote as Finami: partners may offer a new user's first loan at 0%, subject to approval. Terms run from 91 to 120 days. If the 0% does not apply, its sample is ₱1,000 for three months at 48% a year, which comes to ₱1,120. The full APR range is 4% to 916%, so compare offers carefully.
Crezu: one form, a "1st Credit with 0%" headline
Crezu, a brand of Fininity OÜ in Estonia, shows "1st Credit with 0%" on its Philippine homepage, with the footnote "First loan can be free of charge for new clients." It lists ₱500 to ₱25,000 over 91 to 120 days and says Crezu itself charges no service fee. Its general rate range is 12% to a maximum APR of 36%, yet its own example, ₱10,000 over three months repaid as ₱15,000, costs far more than that. We explain the gap in our Crezu review.
Honey Loan: "starting from 0%", with a published normal price
Honey Loan is listed on the SEC list under Warm Cash Lending Corp. (SEC No. 2021030009095). Its offers table shows new clients ₱1,000 to ₱10,000 for up to 12 months, with interest "starting from 0%". The site does not explain when that starting rate applies. What it does publish is the standard price: 0.4% a day and a maximum APR of 144%, with no hidden fees. Its own example: ₱3,000 for 180 days costs ₱2,160, so you repay ₱5,160. Treat 0.4% a day as your planning number unless your disclosure shows 0%. See our Honey Loan review.
Do not chase one promo. Compare all partner offers in one place and pick the one where the total to repay is lowest.
Compare offersWhat about Digido and the other "0%" names?
Search "0 interest loan app" and many blog lists still put Digido at the top for its first-loan promo. Digido's SEC registration was revoked, so we do not list or recommend it. Read what the Digido revocation means if you still have a loan there.
Those lists name other "0% first loan" brands too. We left out any whose own site or app page we could not open and read on 31 October 2026. For an app we did not list, run three checks: its company name on the SEC list, the 0% wording on its own site, and the total to repay in the disclosure statement. Our SEC check guide shows how in two minutes.
How these compare with popular apps
These well-known apps are on the SEC list of 20 October 2026. Their published examples show standard pricing rather than a free first loan, which makes them a useful benchmark for what "not free" costs.
Tala's sample (Google Play, updated 29 October 2026) and Cashalo's (Google Play, updated 12 October 2026) both come out at roughly 0.4% a day once fees are added. That is the price most first-time borrowers pay when no promo applies. If cheap is the goal beyond the first loan, our guide to low interest loan apps compares the published rates.
Real scenarios: does a 0% first loan fit you?
Lea, 26, call-center agent, ₱4,000 short on rent, salary in 18 days. This is the textbook case. She borrows ₱4,000, within the ₱7,000 first-loan limit at Online Loans Pilipinas, and repays the full ₱4,000 two days before the first due date. If the disclosure shows ₱4,000 to repay, it really is free.
Paolo, 31, rider, wants ₱15,000 for a new phone. A 0% first loan will not cover it. First-loan limits sit around ₱7,000 to ₱10,000, and the bigger amounts carry normal rates. Using a matching service like Finami, he might get a first loan at 0% for part of it, but he should price the rest at the normal rate before deciding whether he needs the phone now.
Grace, 38, sari-sari store owner, irregular income. She is not sure the money will be there on the due date. For her, the "free" label is a trap: one late week turns ₱5,000 into a ₱6,220 bill at 0.4% a day, or more. She should borrow less, or pick an ordinary loan with a longer term she can actually meet.
Mark, 22, already used a promo at another app. Promos are per lender, but stacking 0% loans from several apps is how people end up with many due dates in one week. If that is already happening, read what to do after a missed payment before borrowing again.
Red flags dressed up as 0%
A real 0% loan never needs money from you first. Walk away if an app asks for a "processing", "insurance" or "release" fee before sending the loan, says 0% but releases less than you applied for, wants access to your contacts or photos, or has no SEC registration number and Certificate of Authority on its site. Pages copying a real lender's name and logo also use "0%" as bait. Our loan scam red flags guide has more.
Checklist before you take a 0% first loan
- Borrow only the amount you will have in cash on the first due date.
- Check the lender's company name on the SEC's List of Recorded Online Lending Platforms.
- Find the total to repay in the disclosure statement and confirm it equals the amount you receive.
- Check that the full amount lands in your account, with no fee taken out.
- Write down the first payment date and set a reminder three days earlier.
- Ask whether paying early is allowed without a fee.
- Read what happens if you are late: does the normal rate apply from day one?
- Pay the exact balance shown, not a rounded number.
Quick answers
Is there really a 0% interest first loan in the Philippines? Yes. Online Loans Pilipinas, an SEC-recorded lender, says in writing that first-time customers get "zero interest and no processing fee", if repaid on the first payment date. Matching services such as Finami, Binixo and Crezu say partners may offer it, subject to approval.
How much can I borrow at 0% on my first loan? Usually a small amount. Online Loans Pilipinas' website says ₱1,000 to ₱7,000 for first-timers, and Honey Loan caps new clients at ₱10,000.
What happens if I pay my 0% loan late? Expect to lose the promo and pay the normal rate plus a late charge. At 0.4% a day, a ₱5,000 loan over 61 days costs ₱1,220. Under SEC rules for small loans, all charges together can never exceed what you borrowed.
Is a 0% loan app legit? Check the company, not the promo. Online Loans Pilipinas (CS201726430) and Honey Loan's Warm Cash Lending Corp. (2021030009095) are on the SEC list dated 20 October 2026. Digido's registration was revoked.
Does a zero interest loan app charge other fees? It can. Some promos remove interest but keep a processing fee. Look for the total to repay in your disclosure statement.
Can I get a second loan at 0%? Rarely. The promos we read cover the first loan only. Repeat loans are priced at the lender's normal rate.
Still weighing it? Compare offers and choose the one you can repay on time, promo or not.
Sources: SEC List of Recorded Online Lending Platforms as of 20 October 2026; onlineloanspilipinas.ph homepage and FAQ (checked 31 Oct 2026); Online Loans Pilipinas App Store listing (checked 31 Oct 2026); finami.ph, binixo.ph and crezu.ph homepages (checked 31 Oct 2026); honeyloan.ph homepage (checked 31 Oct 2026); Tala Google Play listing (updated 29 Oct 2026) and Cashalo Google Play listing (updated 12 Oct 2026), as summarized in our reviews; SEC Memorandum Circular No. 14, series of 2025 (effective 1 April 2026). Peso examples other than the providers' own are our calculations. This article is general information, not legal or financial advice.
Ready to check your offer with Finami?
Finami
Compare available loan options online
Review the final repayment amount and terms on the provider's website