Home › Blog › Lender and app reviews › Cashalo Review 2026: Interest, Loan Limit, Is It Legit?
Cashalo Review 2026: Interest, Loan Limit, Is It Legit?
Up to ₱13,000 with one valid ID at 0.4% a day. Here is what a Cashalo loan really costs, who it suits and what to do if your limit is too low.
Published November 1, 2026
Your sister's tuition balance is ₱1,800, the school wants it before the exam permit is released, and payday is still two weeks away. A friend says, "Try Cashalo, that's what I use." You search the app, see 10M+ downloads and a 4.7 rating, and then the real questions start. How much will they actually let me borrow? What is the interest in pesos, not percent? And is Cashalo legit, or just another loan app with a nice logo?
We checked Cashalo's Google Play listing (updated 12 October 2026), its own website and the SEC's list of recorded online lending platforms on 31 October 2026. This Cashalo review gives you the numbers in plain pesos, who it suits, where it falls short, and what to do if Cashalo says no or offers you less than you need.
Quick note: Cashalo is not a partner of this site. We earn nothing if you use it. Where we suggest an alternative, we say so clearly.
Cashalo at a glance
Cashalo is a cash loan app run by Paloo Financing, Inc., doing business as Cashalo. The Play listing says Tilt Finance (formerly Empower Finance) is the ultimate parent company, which is why the app shows "Tilt Finance" as the developer. You apply inside the app with your mobile number, pick an amount and a term, and choose where the money goes.
| Feature | What Cashalo publishes |
|---|---|
| Loan amount | ₱1,000 up to ₱13,000 |
| Term | 61 to 180 days |
| Daily cost | 0.4% (0.2% interest + 0.2% fee) |
| Monthly cost | 12% EIR |
| Maximum APR | 144%, all fees included |
| Requirement | 1 valid ID |
| Cash-out | GCash, Maya, GoTyme, BPI, BDO, others |
| Credit bureau | Reports to the CIC |
Is Cashalo legit?
Yes. Paloo Financing, Inc. appears on the SEC's List of Recorded Online Lending Platforms (as of 20 October 2026) with SEC No. CS201800209 and Cashalo as its platform, recorded on 10 October 2019. Its Certificate of Authority is No. 1162, as shown on the app listing and on cashalo.com. If you want to double-check any app yourself, use our guide to checking SEC registration or browse the legit loan apps hub.
Being legit does not make it cheap, and it does not mean you will be approved. It means you are dealing with a licensed company that the SEC can act on if something goes wrong.
Cashalo interest rate: what you really pay
Cashalo's listing breaks the price into two parts: 0.2% a day in interest and 0.2% a day as a service fee. Together that is 0.4% a day, or 12% a month. The listing states a maximum APR of 144% "including all fees". Cashalo also says it releases your loan in full, with no deductions upfront and no advance fees. The charges are added to your repayment schedule instead.
Here is Cashalo's own example. You borrow ₱2,000 for 90 days. Interest is ₱360, the service fee is another ₱360, and you repay ₱2,720 in total.
| Term | Fees on ₱2,000 | Total you repay |
|---|---|---|
| 61 days | ₱488 | ₱2,488 |
| 90 days | ₱720 | ₱2,720 |
| 120 days | ₱960 | ₱2,960 |
| 180 days | ₱1,440 | ₱3,440 |
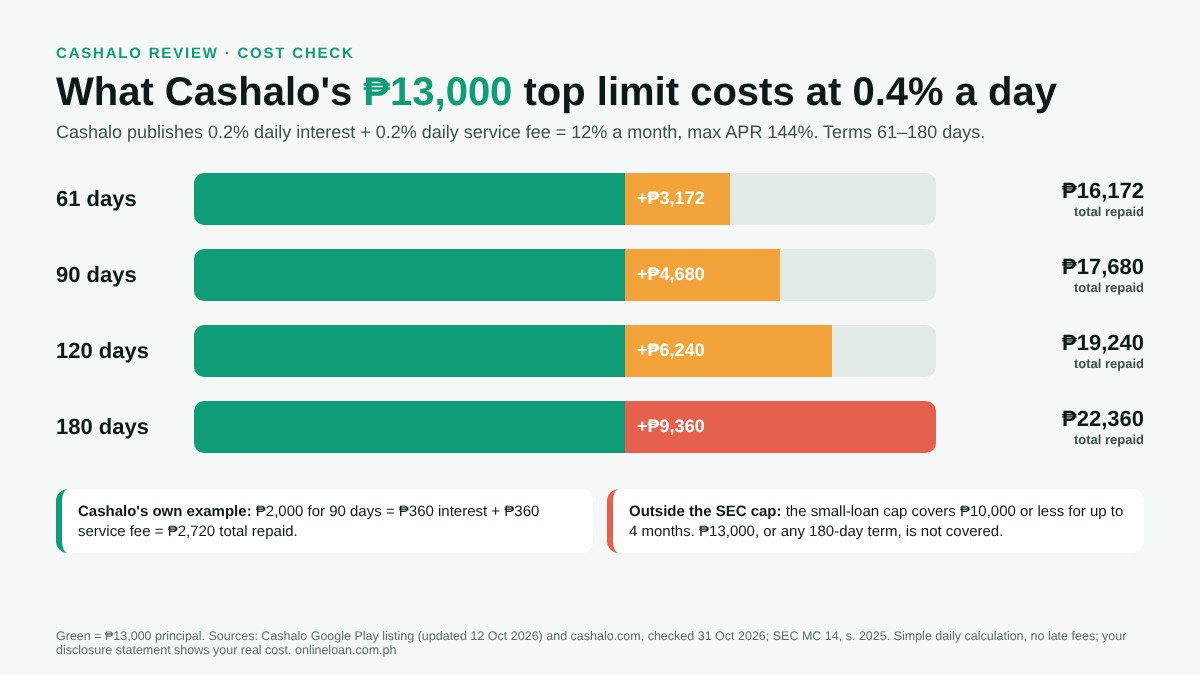
| Term | Fees on ₱13,000 | Total you repay |
|---|---|---|
| 61 days | ₱3,172 | ₱16,172 |
| 90 days | ₱4,680 | ₱17,680 |
| 120 days | ₱6,240 | ₱19,240 |
| 180 days | ₱9,360 | ₱22,360 |
Our calculation: amount × 0.4% × number of days, a simple daily charge as in Cashalo's own example, with no late fees. The 90-day ₱2,000 row matches Cashalo's figure exactly. Your real schedule is in the disclosure statement inside the app.
Key point. At Cashalo, every extra month costs 12% of what you borrowed. Taking ₱13,000 for 180 days instead of 90 adds ₱4,680 to your bill. Pick the shortest term your next paydays can really cover.
Does the SEC rate cap apply to Cashalo?
Partly. Since 1 April 2026, SEC Memorandum Circular No. 14, series of 2025, caps loans of ₱10,000 or less, with terms of up to four months and no collateral. For those loans, interest is capped at 6% a month, the total cost at 12% a month, late penalties at 5% a month on the overdue amount, and all charges together at 100% of the amount borrowed. Cashalo explains these limits on its own website.
So a ₱5,000 loan for 90 days is inside the cap. A ₱13,000 loan, or any loan for 180 days, is outside it. Cashalo still publishes the same 0.4% a day and 144% APR for its full range, but the legal ceiling only protects the smaller, shorter loans. More on this in our 2026 rate cap explainer and our guide to EIR and APR.
Cashalo loan limit: how much can you borrow?
Cashalo's website says loans "start at Php 1,000 and are capped at Php 13,000 for good-paying customers". In practice, that means your first loan is usually far below the ceiling, and the limit grows if you repay on time.
Two honest caveats. First, ₱13,000 is the top of the range, not a promise. Second, some Google Play reviewers say their limit went down, or a new loan was declined, even after paying on time. Cashalo does not publish how it sets or changes limits, so plan as if your next limit could be the same as your last one.
If you need more than ₱13,000, Cashalo is simply not built for it. Look at the alternatives below.
Cashalo requirements and how to apply
The Play listing says you need 1 valid ID, with no collateral and no references. Cashalo's site describes the steps like this:
- Log in to the app with your mobile number.
- Tap "Apply Now" under Cash Loan.
- Complete your profile.
- Choose your loan amount and term.
- Pick a cash-out option: your bank account, GCash or Maya.
- Submit and wait for approval.
How fast is it? The sources do not fully agree. The Play listing promises disbursement "in real-time". Cashalo's cash loan page says approval can take as little as 1 working day, that proceeds are credited in 1 to 3 days, and that minimum disbursement time is "typically less than 24 hrs", depending on cut-off. If you need money tonight, do not count on Cashalo alone.
App permissions to know about
To verify you and assess your credit, the app asks for your location, information about other apps installed on your phone, and SMS data, which Cashalo says it uses to understand your financial activity. Its Data safety section says no data is shared with third parties. If you are not comfortable with SMS access, decide that before you install, not after.
How to repay a Cashalo loan
Cashalo lists these repayment channels: GCash, Maya, ShopeePay, PalawanPay, Cebuana Xpress and 7-Eleven. In GCash, go to Pay Bills, then Loans, then Cashalo, and enter your loan ID and registered mobile number. At 7-Eleven, use the CLIQQ machine. Cashalo's how-to-pay page says the counter adds a ₱20 transaction fee, so e-wallets are cheaper for small payments.
Cashalo does not advertise a minimum payment or extension option. If you miss a payment, its website says additional charges apply, "calculated separately based on the principal", and its payment FAQ warns about late payment fees. For loans inside the SEC cap, penalties cannot go above 5% a month on the overdue amount. If you are already behind, read what happens when you miss a loan payment and contact Cashalo support inside the app early.
Because Cashalo reports to the Credit Information Corporation (CIC), paying on time can help your credit record, and paying late can hurt it.
Cashalo pros and risks
| Pros | Risks |
|---|---|
| Price published: 0.4% a day | Low ceiling: ₱13,000 |
| Loan released in full | Limit can change, reviewers say |
| 1 valid ID, no references | Asks for SMS and app data |
| Many repayment channels | No published extension option |
| Reports good payers to CIC | 180-day loans fall outside SEC cap |
Real scenarios: when Cashalo makes sense
Liza, 29, call center agent, ₱2,000 for her sister's exam permit. She takes 61 days to match two paydays. Cost: ₱488, total ₱2,488. That is inside the SEC cap and a sensible use of Cashalo.
Ramon, 38, tricycle driver, ₱8,000 for a new tire and a repair. He is a repeat Cashalo borrower, but his limit this month is only ₱5,000. Instead of opening three more apps, he takes the ₱5,000, pays the rest from savings and keeps one loan to manage.
Jessa, 33, online seller, wants ₱15,000 for holiday stock. Cashalo cannot go that high. She compares a lender with a higher repeat limit and checks the total cost before signing.
When not to borrow. If you are taking a Cashalo loan to pay off another app, stop. Two loans at 12% a month each grow faster than most salaries.
Cashalo vs Honey Loan and other alternatives
If Cashalo's limit is too low or you were declined, the closest like-for-like option on our partner list is Honey Loan. We chose it as the alternative here because it publishes the same price, 0.4% a day with a 144% maximum APR, but with a higher ceiling. Honey Loan's website, checked 31 October 2026, lists ₱1,000 to ₱30,000, with new clients up to ₱10,000 and repeat clients up to ₱30,000, terms of 61 to 364 days, and a minimum payment that moves your due date by 7, 14 or 30 days. Its operator, Warm Cash Lending Corp., is on the same SEC list. The trade-off: you must be 21 to 70, and long terms cost more in total. Our Honey Loan review covers it in full.
- Warm Cash Lending Corp., on the SEC list
- New clients up to ₱10,000, repeat up to ₱30,000
- Minimum payment moves your due date 7, 14 or 30 days
- Age 21 to 70; long terms raise the total cost
- Sofi Financing Inc., SEC No. CS201908275
- Minimum payment option to move your due date
- Rate is shown only during the application
Other SEC-recorded apps people compare with Cashalo:
Cashalo limit too low? See which SEC-recorded lenders and matching services can offer more, with the total repayment shown before you sign.
Compare offersChecklist before you borrow from Cashalo
- Decide the exact amount you need, not the limit the app offers.
- Check that the total repayment in the disclosure statement matches 0.4% a day.
- Choose the shortest term your next one or two paydays can cover.
- Keep the loan at ₱10,000 or less and 4 months or shorter if you want the SEC cap to protect you.
- Pay through GCash or Maya to avoid the ₱20 counter fee.
- Set a reminder two days before each due date.
- Never pay anyone a "release fee". Cashalo says it charges no advance fees.
Quick answers
Is Cashalo legit? Yes. Paloo Financing, Inc. (Cashalo) is on the SEC's list of recorded online lending platforms as of 20 October 2026, SEC No. CS201800209, Certificate of Authority No. 1162.
What is Cashalo's interest rate? 0.4% a day in total: 0.2% interest plus a 0.2% service fee. That is 12% a month, with a maximum APR of 144% including all fees.
What is the Cashalo loan limit? Loans start at ₱1,000 and go up to ₱13,000 for good-paying customers. First loans are usually smaller.
What are the Cashalo requirements? One valid ID, a mobile number and a completed profile in the app. No collateral or references, according to its Play listing.
How long can I pay a Cashalo loan? Terms run from 61 to 180 days.
Can I borrow more than ₱13,000? Not from Cashalo. Lenders such as Honey Loan go up to ₱30,000 for repeat clients.
Still deciding? Compare offers, read the disclosure statement line by line, and borrow only what your next paydays can repay.
Sources: Cashalo Google Play listing, com.oriente.cashalo (updated 12 Oct 2026, checked 31 Oct 2026); cashalo.com cash loan page, how-to-pay page and April 2026 rate cap notice (checked 31 Oct 2026); SEC List of Recorded Online Lending Platforms as of 20 October 2026; SEC Memorandum Circular No. 14, series of 2025 (effective 1 April 2026), as summarized by Cashalo; honeyloan.ph homepage and how-to-repay page and finbro.ph FAQ (checked 31 Oct 2026). Peso examples other than Cashalo's own are our calculations. This article is general information, not legal or financial advice.
Ready to check your offer with Honeyloan?
Honeyloan
Compare available lending offers
Review the final repayment amount and terms on the provider's website