Home › Blog › Lender and app reviews › Home Credit Cash Loan Review: Rates and Real Costs
Home Credit Cash Loan Review: Rates and Real Costs
Home Credit's cash loan can be one of the cheaper app loans or one of the priciest. It all depends on the rate in your offer, so here is the math in pesos.
Published October 30, 2026
You open the My Home Credit app and there it is: a "pre-approved" cash loan offer for ₱15,000. Tuition is due, the laptop just died, or the roof needs fixing before the rains get worse. One tap and the money can be in your bank account in about a minute. The question is not whether Home Credit can lend you the money. It is what that ₱15,000 will cost you by the time you make the last payment.
Home Credit is one of the biggest consumer lenders in the country. Most Filipinos know it from the appliance and gadget counters at malls, where it sells installment plans. Its cash loan is a different product with different rules, and the price swings a lot depending on the rate in your personal offer.
This review shows who can actually get one, what it costs in pesos at the low and high end, the late charges nobody reads, and when another option is better.
Is Home Credit legit?
Yes. Home Credit is run by HC Consumer Finance Philippines, Inc. (SEC No. CS201301354, Certificate of Authority No. 1071), and its app "My Home Credit" is on the SEC's List of Recorded Online Lending Platforms dated 20 October 2026.
It is also a large, well-funded company. Thailand's Krungsri, part of Japan's MUFG group, owns 75% of it, and Security Bank completed the purchase of the other 25% for ₱10.36 billion, according to the Inquirer (May 2025). Home Credit says it has served more than 13 million customers and works with over 18,000 partner stores. For a wider list of registered apps, see our guide to legit loan apps in the Philippines.
Home Credit cash loan at a glance
| Feature | Home Credit cash loan |
|---|---|
| Operator | HC Consumer Finance Philippines, Inc. |
| Loan amount | ₱3,000–₱150,000 |
| Terms | 6–48 months (app listing) |
| Monthly rate | 2.49%–8.49% (app listing) · from 2.32% (website) |
| Processing fee | 3%, max ₱1,000 (app listing) · up to ₱500 (disclosures) |
| Who can apply | Ages 18–68 · existing customers |
| Payout | Bank transfer or cash pick-up |
| Google Play | 4.8 stars · about 533K reviews · 10M+ downloads |
Sources: Home Credit Google Play listing and homecredit.ph cash loan and disclosure pages, checked 30 October 2026.
Notice that Home Credit's own pages do not agree. The Google Play listing gives a monthly rate of 2.49% to 8.49% (30% to 102% a year) and a processing fee of 3%, capped at ₱1,000. The cash loan page says rates start at 2.32% a month. The disclosure page, marked "updated as of October 2025", lists a nominal rate of 1.49% to 8.99% a month, an average effective rate of 3.89% a month and a processing fee of up to ₱500. Your offer and disclosure statement are what count.
The catch for new borrowers: cash loans are for existing customers
This is the part many people miss. Home Credit's cash loan page says it currently provides cash loans to existing customers. If you have never bought anything on a Home Credit installment plan, you will usually not see a cash loan offer at all, and if you are rejected, Home Credit says you can only reapply once you receive a new offer.
The usual path is to start with a product loan at a partner store, such as a phone or appliance on installment, pay it on time, and wait for a cash loan offer to appear in the app. If you need cash now and have no history with Home Credit, it is the wrong place to start.
What a Home Credit cash loan really costs
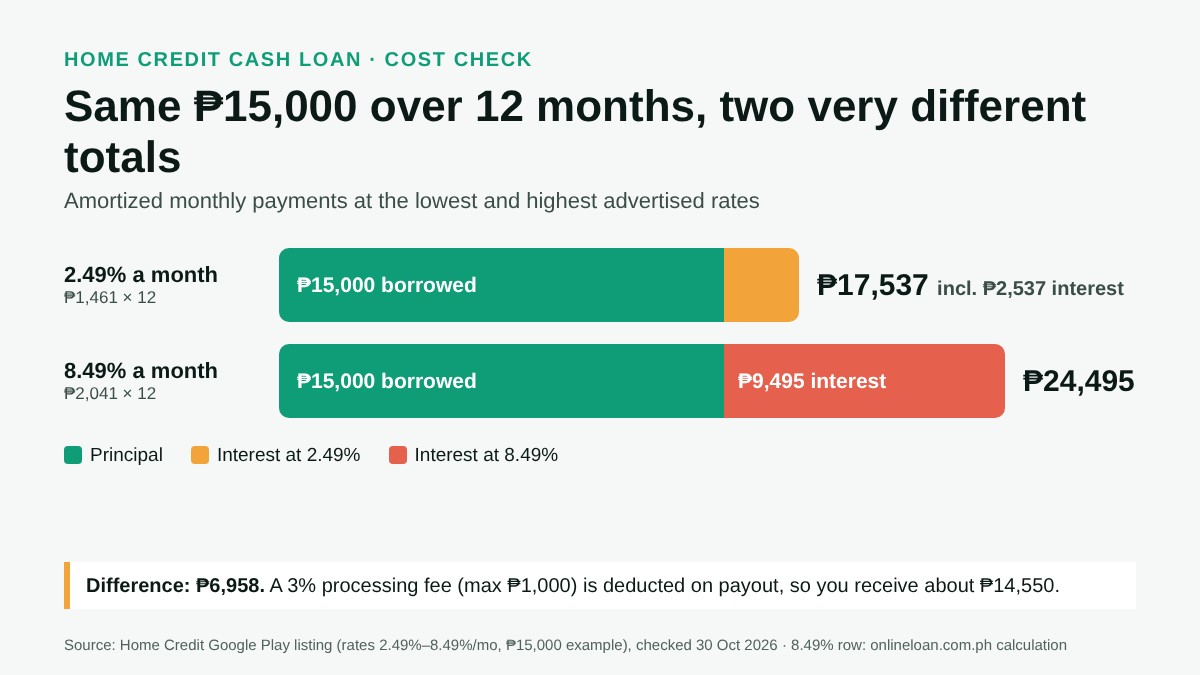
Home Credit's own example on Google Play is a ₱15,000 loan over 12 months at 2.49% a month. You pay ₱1,461 a month, for a total of ₱17,537. We checked the math with code: it is a standard amortized loan, where interest is charged on the remaining balance, not the original amount. That is fairer than the add-on interest many apps use.
The processing fee changes the picture slightly. If 3% is deducted, you receive ₱14,550 but still repay ₱17,537, so the true monthly cost is about 3.0%, not 2.49%. The bigger risk is the rate itself. Your offer can be anywhere in the range, and the top of the range is a very different loan.
| Loan and rate | Monthly · total repaid | True monthly cost |
|---|---|---|
| ₱15,000 · 12 mo · 2.49% | ₱1,461 · ₱17,537 | About 3.0% |
| ₱15,000 · 12 mo · 8.49% | ₱2,041 · ₱24,495 | About 9.1% |
| ₱10,000 · 6 mo · 2.49% | ₱1,815 · ₱10,889 | About 3.4% |
| ₱30,000 · 24 mo · 2.49% | ₱1,676 · ₱40,213 | About 2.8% |
How we calculated: the first row is Home Credit's own example. The other rows use the same amortized method at the lowest and highest rates on the Google Play listing. "True monthly cost" assumes the 3% processing fee (capped at ₱1,000) is deducted from what you receive, and is the rate at which the payments repay the cash you actually get. Your offer may differ.
The gap between the first two rows is ₱6,958 on the same ₱15,000. So look at the rate in your offer before tapping "accept", not just the monthly amount.
Key point. At its lowest advertised rate, a Home Credit cash loan is one of the cheaper app-based loans, at about 3% a month all-in for a 12-month loan. At the top rate, the same ₱15,000 costs nearly ₱7,000 more. Check the rate and the total repayment in your offer, not just the monthly installment.
Because Home Credit cash loans run for at least six months, they generally sit outside the 2026 small-loan ceilings, which cover loans of ₱10,000 or less with terms of up to four months. Our guide to the 2026 interest rate cap explains what is covered, and our explainer on how loan interest rates work shows how to compare add-on and amortized rates.
Before you accept any offer, it is worth a two-minute check of what else you qualify for. You can compare offers from our partners and set the total repayment side by side with your Home Credit number.
Real-life scenarios: when Home Credit fits
"I need ₱15,000 for school fees and can pay ₱1,500 a month." This is Home Credit's sweet spot, if your offer is near the low end of the range. Twelve fixed payments of about ₱1,461 are predictable. Set up auto debit so you never miss a due date.
"My offer is ₱15,000, but the rate shows 8% a month." Stop and compare. At 8.49%, you would repay about ₱24,500. A store 0% installment, a salary loan from your employer, or an offer from another registered lender could save you thousands.
"Payday is a week away and I need ₱5,000." Home Credit is not built for this. The shortest term is six months, and paying the whole loan early carries a ₱300 early repayment fee, according to its disclosures. A short-term loan or a pay-later option fits a one-week gap better. Our comparison of loan apps, banks and pawnshops can help.
"I have never used Home Credit." You probably will not get a cash loan offer yet. Start with a store installment you were going to buy anyway, pay it on time, and the cash loan offer may follow.
How to apply and get the money
You can apply in the My Home Credit app, at a partner store, or through the hotline number in an offer message. Home Credit asks for primary and secondary IDs, such as the Philippine National ID, UMID or a driver's license, plus an NBI clearance, barangay certificate or utility bill.
Approval can take as little as a minute, and Home Credit says the money is released within a minute of approval. You can receive it by bank transfer to one of 10 partner banks, including BPI, BDO, Metrobank and RCBC, or as cash pick-up at partners such as Palawan Express and Cebuana Lhuillier. Bring one valid ID with your address and your reference number. If you do not claim the money within seven days, the contract is cancelled.
You can repay by auto debit, in the app, on the website with a debit card, or over the counter at payment partners.
What happens if you pay late
This is where Home Credit gets expensive. Its disclosure page (updated October 2025) lists these charges for cash loans:
| Days unpaid | Charge (up to) |
|---|---|
| 5 days | ₱300 |
| 30 days | ₱700 |
| 60 days | ₱1,000 |
| 90 days | 40% of outstanding principal |
| Every 120 days after, to 270 | 2% of outstanding principal |
The 90-day "termination fee" is the one to fear. On a ₱10,000 outstanding principal, 40% is ₱4,000 on top of what you already owe. If you see trouble coming, contact Home Credit before the due date. In March 2026, Home Credit said customers with temporary money problems, such as medical bills or a job change, can ask for help through its Payment Support Program, which may allow flexible payment terms for a limited period (Context.ph, 4 March 2026). Our guide on what happens if you miss a loan payment explains your options.
Collection: the June 2026 SEC fine
Be aware of one recent case. In an order dated 3 June 2026, the SEC fined HC Consumer Finance Philippines ₱50,000 for collecting a debt at a residence of people who were neither guarantors nor co-makers of the loan, even after the borrower objected in writing, the Inquirer reported. The SEC ordered the company to stop this practice and revise its collection policies. Home Credit has appealed and said it takes regulatory matters seriously, according to Insider PH (20 June 2026). We found no report on the outcome yet.
The rule is simple: collectors may contact you, and guarantors or co-makers you named, but not your neighbors, relatives or contacts. If that happens, our guide on how to report loan harassment shows where to complain.
Pros and risks
| Pros | Risks |
|---|---|
| On the SEC list dated 20 Oct 2026 | Rate range is wide: 2.49%–8.49% a month |
| Amortized interest, not add-on | Cash loans mostly for existing customers |
| Up to ₱150,000 and up to 48 months | Heavy late charges, 40% at 90 days |
| Fast payout to bank or pick-up | ₱300 early repayment fee |
| Large, bank-backed company | SEC fine over collection in June 2026 |
Before you accept a Home Credit offer: a checklist
- Download My Home Credit only from Google Play or the App Store, published by HC Consumer Finance Philippines, Inc.
- Find the monthly interest rate in your offer, not just the installment amount.
- Write down the total amount you will repay and the amount you will actually receive after the processing fee.
- Compare that total with at least one other registered lender.
- Choose a term you can afford without stretching it longer than needed.
- Set up auto debit or a phone reminder a few days before every due date.
- If you might be late, call Home Credit before the due date, not after.
- Never pay an "agent" or a personal account. Pay only through official channels and keep receipts.
Quick answers
Is Home Credit legit? Yes. HC Consumer Finance Philippines, Inc. (SEC No. CS201301354) is on the SEC's List of Recorded Online Lending Platforms dated 20 October 2026, with "My Home Credit" as its registered platform.
What is Home Credit's cash loan interest rate? The Google Play listing gives 2.49% to 8.49% a month (30% to 102% a year). The website says rates start at 2.32% a month, and the disclosure page lists 1.49% to 8.99%. Your offer decides your rate.
How much can I borrow from Home Credit? From ₱3,000 to ₱150,000, depending on your personal offer, with terms of 6 to 48 months according to the app listing.
Can I get a Home Credit cash loan as a first-time customer? Usually not. Home Credit says it currently offers cash loans to existing customers. Most people start with a store installment and get a cash loan offer later.
How fast is the Home Credit cash loan released? Home Credit says money is disbursed within a minute of approval, to a partner bank or for cash pick-up.
What happens if I don't pay Home Credit? Charges of up to ₱300 at 5 days, ₱700 at 30 days and ₱1,000 at 60 days, then a termination fee of 40% of outstanding principal at 90 days.
Compare before you say yes
A Home Credit cash loan can be a fair deal: amortized interest, fixed payments and fast payout from a big, registered lender. But the rate range is wide, and the late charges are steep. Before you accept, compare offers from our partners on the total amount to repay, and pick the one you can pay on time every month.
Sources: Home Credit Google Play listing (updated 9 October 2026, checked 30 October 2026); homecredit.ph homepage, cash loan page and disclosures page (updated October 2025), checked 30 October 2026; SEC List of Recorded Online Lending Platforms as of 20 October 2026; Inquirer, May 2025 and June 2026; Insider PH, 18 and 20 June 2026; Context.ph, 4 March 2026. Peso examples other than Home Credit's own are our calculations. This article is general information, not legal or financial advice.
Ready to check your offer with Finbro?
Finbro
Compare available lending offers
Review the final repayment amount and terms on the provider's website