Home › Blog › Best loan apps by need › Loan Apps With 1 Valid ID Philippines: 7 Options 2026
Loan Apps With 1 Valid ID Philippines: 7 Options 2026
One valid ID can be enough for a first loan. Here is which apps accept it, which IDs work best, and what the loan costs in pesos.
Published November 1, 2026
Payday is on the 15th, it is only the 9th, and the clinic wants ₱4,500 for your daughter's check-up and medicines. You open a loan app, and the first screen asks for a company ID, a certificate of employment and three months of payslips. You close it. In your wallet there is exactly one thing a lender might want: your UMID, or your driver's license, or the PhilSys ID that finally arrived last year.
Good news: for small amounts, one ID really can be enough. Several lenders on the SEC list say in writing that they only ask for a single valid ID, sometimes with a selfie. The fine print is what "only" means: the app still checks you, still prices the loan, and still decides how much you get.
We checked what each provider says on its own website or Google Play listing on 1 November 2026 (Tala and Cashalo: listings updated in October 2026). Below you will find which apps accept one ID, which IDs work best, what the loan costs in pesos and what to do if the app rejects your ID. This site is a comparison service, not a lender, and some partners pay us a referral fee when you apply.
7 loan apps and services that accept 1 valid ID
The first four are lenders: the company that signs the loan with you. All four are on the SEC's List of Recorded Online Lending Platforms dated 20 October 2026. The last three are matching services: free sites that pass one application to several lenders, which then run their own checks.
- Accepts SSS, UMID, driver's license, passport, national ID, postal ID
- "No payslip document required", per its homepage
- Decision in 10 minutes to 1 working day
- Paid out to GCash, Maya or a bank account
- Age 20–70 and a regular income; rate shown only in the application
- "You only need your ID to apply", its homepage says
- Valid government ID and an active, unblocked mobile number
- 0.4% a day, maximum APR 144%, published
- Repeat clients up to ₱30,000, terms 61–364 days
- Age 21–70; every application gets a credit check
- "Only 1 valid ID is needed", per its Google Play listing
- No income proof and no bank account needed, 18+
- Up to 120 days, repay any time
- Fees are personalised: 3.99–9.99% + 0.23–0.43% a day
- "1 Valid ID, no collateral or references needed"
- 61–180 days, 0.4% a day
- Paid out to GCash, Maya, GoTyme, BPI, BDO
- Uses SMS, location and installed-app data to assess you
- "You may only need one valid ID and a selfie", depending on the provider
- Repayment from 91 to 180 days
- APR from 0% to 427%, depending on the lender
- Not a lender: check who approves you
- Asks for a valid PH ID and a bank account
- Free for you, terms of 91 to 120 days
- Not a lender: check who approves you
- Lists two requirements: age 18+ and a valid government ID
- Free for users; terms of 91 to 120 days
- APR between 4% and 916%, depending on the lender
- Not a lender: check who approves you
Tala and Cashalo are not partners of this site; we include them because their Google Play listings say plainly that one ID is enough. For the full list of registered apps, see our legit loan apps hub.
How we chose these options
An app or service made this list only if it passed four tests. Commission was not one of them.
- It says so in writing. The "one ID" requirement had to appear on the provider's own website or app listing, not in an ad or a reseller's post.
- Lenders are regulated. Every lender here was on the SEC list dated 20 October 2026 when we checked it on 1 November 2026.
- Matching services say they are not lenders. Loanonline, Crezu and Binixo are labelled clearly, because the real decision is made by the lender they pass you to.
- You can find the price. Published rates got credit. Where a lender shows its price only inside the application, we say so.
Which valid ID works best for a loan app?
"1 valid ID" usually means one government-issued photo ID with your full name, your birthday and a clear photo. Finbro is the only lender above that publishes its accepted list: SSS, UMID, driver's license, passport, national ID (PhilSys) and postal ID. The others simply say "valid ID" or "valid government ID", so pick the strongest one you have.
| Your ID | How it usually goes | Tip |
|---|---|---|
| PhilSys national ID | Strong choice | Use the card, not a blurry photo of it |
| UMID or SSS ID | Strong choice | Check the name matches your e-wallet |
| Driver's license | Strong choice | It must not be expired |
| Passport | Strong choice | Photograph the photo page, flat and bright |
| Postal ID | Accepted by Finbro | Not every app lists it |
| School or company ID | Usually not enough | Use a government ID instead |
Our documents guide explains each ID in more detail.
The selfie is part of the ID check
Finbro asks for a selfie with your ID, and many lenders that Loanonline and Crezu connect you to do the same. The app matches your face with the ID photo. Most failed checks we hear about are boring: a dark room, glare on a laminated card, a cropped corner, or a selfie taken with a filter. Take both photos by a window in daylight, with the whole card in frame.
Your name must match everywhere
The name on your ID, your e-wallet and your bank account should be the same, including the middle name. A loan approved to "Ma. Cristina" cannot always be sent to a GCash account registered as "Maria Cristina". If your married name is on one and your maiden name on the other, sort that out before you apply.
Key point. "1 valid ID" describes the paperwork, not the decision. The ID gets your application read; your phone data, credit history and repayment capacity decide whether you get ₱1,000, ₱10,000 or a no.
Have your ID ready? Check what you qualify for with an SEC-recorded lender that asks for one ID and a selfie.
Check your Finbro offerThe options in detail
Finbro: one ID, a selfie and a regular income
Finbro is run by Sofi Financing Inc. (SEC No. CS201908275, Certificate of Authority No. 1324). Its homepage, checked on 1 November 2026, says it "only takes one valid ID and selfie to proceed" and adds "No payslip document required". The other conditions: Filipino citizen, age 20 to 70, and a stable income from a job or another regular source.
Decisions take from 10 minutes to one working day, and approved loans are sent in real time to GCash, Maya or a bank account. Finbro does not publish a rate table: the interest rate and processing fee appear in the application, before you confirm. Read that screen slowly. Full details are in our Finbro loan review.
Honey Loan: the ID-only lender with a published price
Honey Loan is run by Warm Cash Lending Corp. (SEC No. 2021030009095, Certificate of Authority No. 3472). Its homepage says "You only need your ID to apply", and its requirements are short: a Filipino citizen aged 21 to 70, a valid government ID, an active mobile number that is not blocked, and an account on its website.
The price is printed: 0.4% a day and a maximum APR of 144%. Its own example is ₱3,000 for 180 days, which costs ₱2,160 in interest and fees, so you repay ₱5,160 in six installments of ₱860. New clients can borrow ₱1,000 to ₱10,000; repeat clients up to ₱30,000. See our Honey Loan review.
Tala and Cashalo: two big "1 valid ID" apps
Tala's Google Play listing (updated 29 October 2026) says "Only 1 valid ID is needed", with no income proof and no bank account required, for users 18 and up. Limits run from ₱1,000 to ₱25,000 for up to 120 days. Its listing gives an example of ₱1,000 for 61 days with ₱1,240.20 to repay.
Cashalo's listing (updated 12 October 2026) asks for "1 Valid ID" and no collateral or references. It lends ₱1,000 to ₱13,000 for 61 to 180 days at 0.4% a day, and its own example is ₱2,000 for 90 days with ₱2,720 to repay. Neither is our partner; see the Tala review and Cashalo review.
Loanonline, Crezu and Binixo: one form, several lenders
These three are matching services. You fill in one form, and they pass your details to lenders that may make an offer. Loanonline says that, depending on the provider, you "may only need one valid ID and a selfie", for requests up to ₱25,000 over 91 to 180 days. Crezu asks for a valid PH ID and a bank account, for ₱500 to ₱25,000. Binixo lists only two requirements, age 18+ and a valid government ID, for requests up to ₱25,000 over 91 to 120 days.
The upside is reach: one form, several chances. The catch is that the lender you end up with sets its own rules and price. Before you accept an offer, find the lender's company name and check it on the SEC list. Our guide on how to check if a lender is SEC-registered takes two minutes.
What a 1-ID loan costs in pesos
Asking for one ID does not make a loan more expensive by itself. What matters is the rate, the term and whether you pay on time. Here is what the published prices mean on everyday amounts.
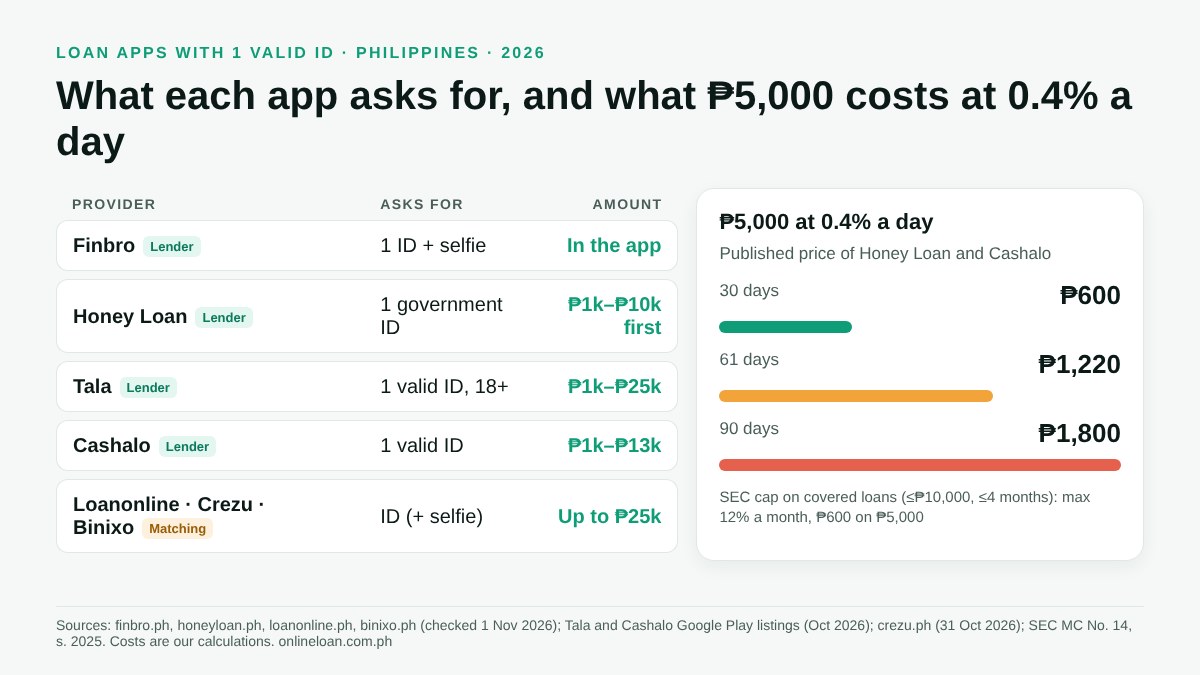
| Loan | Cost | Total to repay |
|---|---|---|
| ₱3,000 at 0.4% a day, 61 days | ₱732 | ₱3,732 |
| ₱5,000 at 0.4% a day, 30 days | ₱600 | ₱5,600 |
| ₱5,000 at 0.4% a day, 90 days | ₱1,800 | ₱6,800 |
| Honey Loan example: ₱3,000, 180 days | ₱2,160 | ₱5,160 |
| Cashalo example: ₱2,000, 90 days | ₱720 | ₱2,720 |
| Tala example: ₱1,000, 61 days | ₱240.20 | ₱1,240.20 |
How we worked these out. The 0.4% rows are the loan × 0.4% × days, the published daily price of Honey Loan and Cashalo, without late fees. The example rows are the lenders' own figures from their website or Google Play listing. Your real cost is the one in your disclosure statement.
Small loans have a legal ceiling too. Under SEC Memorandum Circular No. 14, series of 2025, in force since 1 April 2026, unsecured loans of ₱10,000 or less with terms up to four months may cost at most 12% a month in interest and fees, and all charges together may never exceed the amount borrowed. On a ₱5,000 loan that is at most ₱600 a month. Our 2026 rate cap explainer has the details.
Your ID was rejected? What to do next
A rejected ID is not the end of the road. Work through these causes in order.
- Blurry or cropped photo. Retake it in daylight, card flat on a table, all four corners visible.
- Expired ID. Use another one. A driver's license or passport past its date is a common reason for a fail.
- Name mismatch. Your ID, e-wallet and bank account must carry the same name.
- Not on the app's list. Postal and SSS IDs are accepted by Finbro but not named by every app. Try a PhilSys ID, UMID, passport or driver's license.
- Too young for that lender. Finbro starts at 20 and Honey Loan at 21. Tala and Binixo list 18+.
- The ID was fine, the profile was not. If the app accepted your ID but declined the loan, wait before applying again, and read our tips to improve your approval chances.
Real scenarios: when one ID is enough
Mylene, 32, sari-sari store owner, needs ₱4,000 for stock before the weekend. She has a PhilSys ID and a GCash account in the same name. Honey Loan's ID-only application suits her: at 0.4% a day, ₱4,000 for 61 days costs ₱976. She picks the shortest term her sales can cover.
Rico, 19, college working student, needs ₱2,000 for a laptop repair. He is under Finbro's and Honey Loan's minimum ages. Tala lists 18+, and Binixo passes requests from 18-year-olds to lenders that may accept him. He borrows the smallest amount and repays from his part-time pay.
Ate Joy, 41, domestic helper, has only a postal ID. Finbro's FAQ names the postal ID on its accepted list, so she can apply with it plus a selfie. She checks the total on the offer screen before confirming.
Dennis, 27, wants ₱15,000 for a new phone with just his ID. A first loan of that size with one ID is unlikely: Honey Loan caps new clients at ₱10,000, and other apps start most people low. Our advice: wait for the sale to pass, or save for it. For bigger needs, see our ₱10,000 loan guide.
How these compare with other popular apps
Other apps you will see in the Play Store, all on the SEC list of 20 October 2026, but with different paperwork or access rules:
No payslip at all? Our guide to a loan without a payslip covers SSS and bank routes that use contributions or business papers instead.
Red flags: "ID lang, approved agad"
Scammers love the "one ID" pitch because it sounds easy. Walk away if a page or agent asks you to send your ID and selfie over Messenger, Viber or Telegram, asks for a fee before the loan is released, promises "guaranteed approval", or has no SEC registration number and Certificate of Authority on its site. Your ID photo plus a selfie is exactly what fraudsters need to open accounts in your name. Upload them only inside the official app or website. More warning signs: loan scam red flags.
Checklist before you apply with one ID
- Choose your strongest ID: PhilSys, UMID, driver's license or passport, not expired.
- Make sure your name is identical on the ID, your e-wallet and your bank account.
- Take the ID photo and selfie in daylight, without filters, with the whole card in frame.
- Check the lender's company name on the SEC list before you upload anything.
- Ask for the smallest amount that solves the problem.
- On the offer screen, write down the amount you receive, the total to repay and the due date.
- Set a reminder two days before the due date.
- Never pay a fee before the loan is released.
Quick answers
Which loan app needs only 1 valid ID in the Philippines? Honey Loan says you only need your ID to apply. Tala and Cashalo say "1 valid ID" in their Google Play listings. Finbro asks for one valid ID and a selfie.
What IDs are accepted for an online loan? Finbro accepts SSS, UMID, driver's license, passport, national ID and postal ID. Other apps say "valid government ID", so a PhilSys ID, UMID, passport or driver's license is the safest choice.
Can I get a loan with 1 valid ID and no payslip? Yes, at some lenders. Finbro says no payslip document is required and Tala says no income proof is needed, but both still assess you.
How much can I borrow with 1 valid ID? First loans are usually small. Honey Loan lends new clients ₱1,000 to ₱10,000, Cashalo up to ₱13,000 and Tala ₱1,000 to ₱25,000, depending on your profile.
Is Finbro legit? Finbro.ph is run by Sofi Financing Inc. (SEC No. CS201908275) and was on the SEC's list of recorded online lending platforms dated 20 October 2026.
Can I get a 1-ID loan sent to GCash? Yes. Finbro and Cashalo list GCash and Maya as payout options. Use an e-wallet registered in the same name as your ID.
Want a ranking by situation instead? See our best online loan apps, or go straight to Finbro for an ID-and-selfie application from an SEC-recorded lender.
Sources: finbro.ph homepage and FAQ (checked 1 Nov 2026); honeyloan.ph homepage (checked 1 Nov 2026); Tala Google Play listing (updated 29 Oct 2026); Cashalo Google Play listing (updated 12 Oct 2026); loanonline.ph and binixo.ph homepages (checked 1 Nov 2026); crezu.ph homepage (checked 31 Oct 2026); SEC List of Recorded Online Lending Platforms as of 20 October 2026 (checked 1 Nov 2026); SEC Memorandum Circular No. 14, series of 2025. Peso examples other than the lenders' own are our calculations. This article is general information, not legal or financial advice.
Ready to check your offer with Finbro?
Finbro
Compare available lending offers
Review the final repayment amount and terms on the provider's website